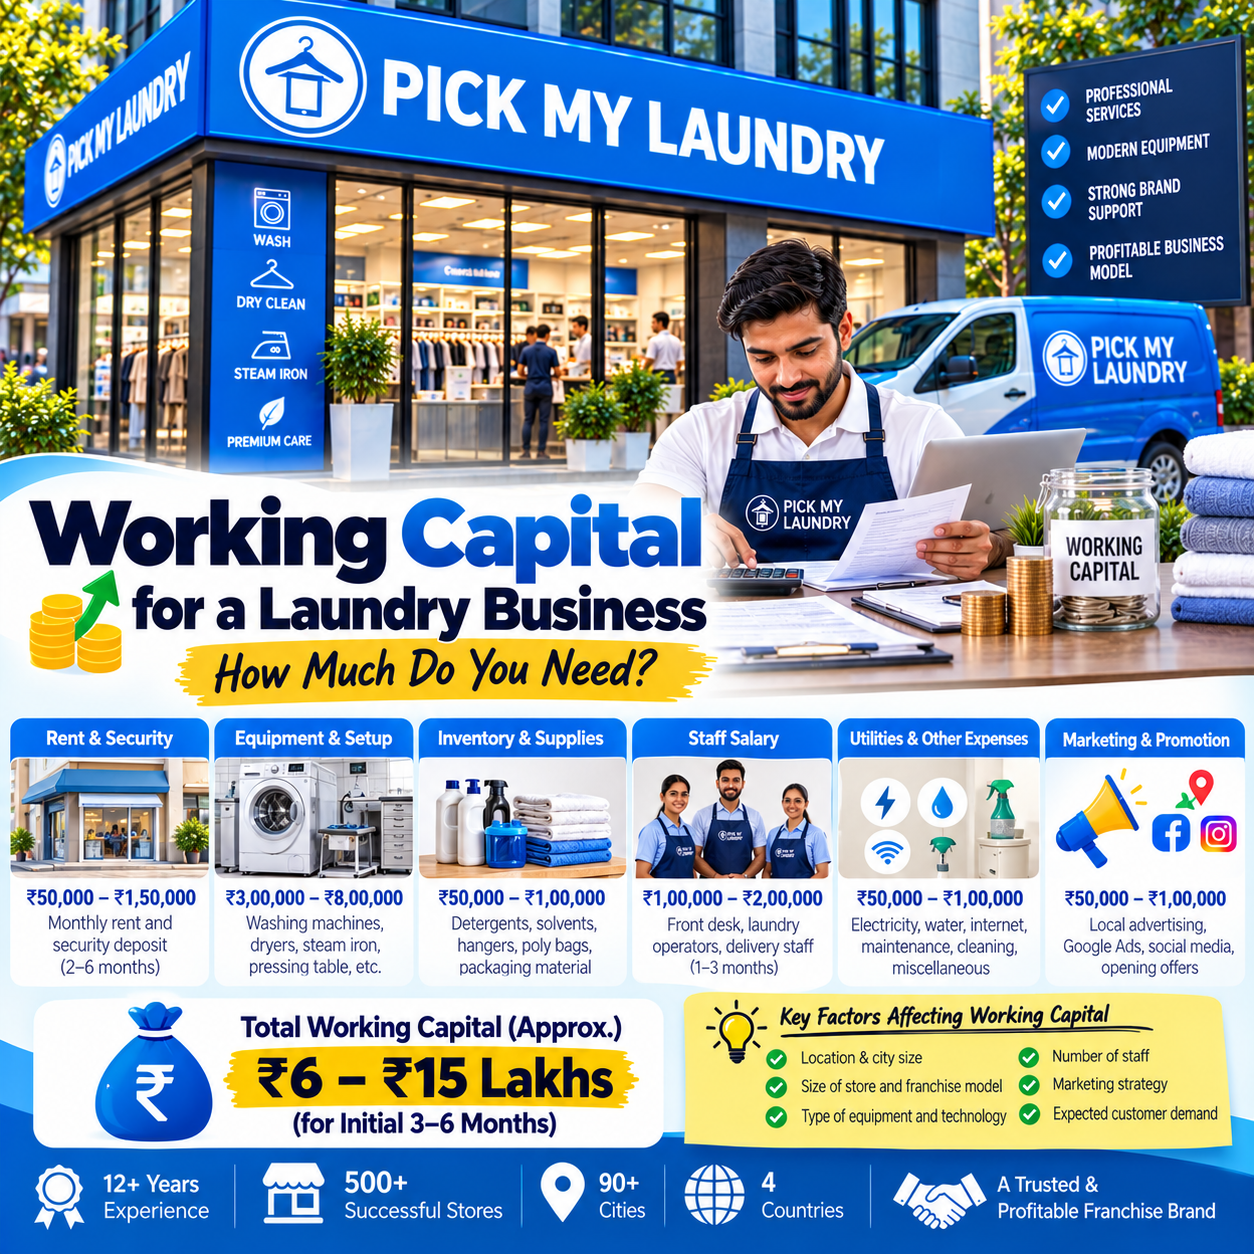
Working Capital for a Laundry Business: How Much Do You Need?
Working Capital for a Laundry Business: How Much Do You Need?
When entrepreneurs calculate the cost of starting a laundry or dry-cleaning business, they often focus on the store, equipment and interiors.
But there is another financial requirement that can be equally important:
Working capital.
Working capital is the money available to manage the business's day-to-day expenses while revenue is being generated.
For a new laundry business, customer demand may take time to develop. Meanwhile, expenses such as rent, salaries, utilities, packaging, transportation and marketing continue.
Therefore, a proper working capital plan for a laundry business should be prepared before launch.
Important: There is no universal working-capital amount for every laundry business. Requirements vary by city, rent, staff, business model, service mix, order volume and operating structure. The examples below are for financial-planning purposes only.
What Is Working Capital?
In simple terms:
Working Capital = Current Operating Resources − Current Operating Liabilities
For a small business owner, however, the practical question is often:
“How much cash should I keep available to run my business until operations become stable?”
For a new laundry outlet, this reserve may be used for:
- Rent
- Salaries
- Utilities
- Packaging
- Consumables
- Transportation
- Marketing
- Maintenance
- Technology
- Administrative expenses
- Unexpected operating costs
Why Working Capital Matters in a Laundry Business
A new laundry store doesn't necessarily reach its mature customer volume from day one.
The business may experience:
Launch → Customer Acquisition → Growing Orders → Repeat Customers → More Stable Operations
During this period, monthly revenue and expenses may not move at the same speed.
For example, your store may have fixed monthly expenses even when customer orders are still developing.
That is why working capital acts as an operating cushion.
1. Start by Calculating Monthly Fixed Expenses
The first step is to calculate your recurring expenses.
These may include:
Rent
Your monthly property cost.
Salaries
Store staff, processing staff, delivery staff or management.
Utilities
Electricity, water and other applicable utilities.
Technology
Software, POS or other technology-related charges.
Marketing
Digital advertising and local marketing.
Maintenance
Equipment and store maintenance.
Administration
Accounting, communication and other recurring expenses.
Example Monthly Fixed Expense Structure
| Expense | Illustrative Amount |
|---|---|
| Rent | ₹50,000 |
| Salaries | ₹80,000 |
| Utilities | ₹25,000 |
| Marketing | ₹20,000 |
| Technology | ₹10,000 |
| Maintenance | ₹10,000 |
| Administration | ₹5,000 |
| Total | ₹2,00,000 |
These figures are illustrative only and should not be treated as standard Pick My Laundry expenses.
2. Calculate Variable Operating Costs
Not every expense stays fixed.
Some costs increase as order volume increases.
These can include:
- Packaging
- Consumables
- Processing-related costs
- Pickup and delivery
- Payment charges
- Order-level materials
For example, if your store processes more orders, packaging and transportation requirements may also increase.
Therefore, your working-capital model should consider both:
Fixed Costs + Variable Costs
3. Include Employee Costs
Manpower is a recurring expense that should be planned carefully.
Depending on the outlet format, employees may include:
- Store manager
- Customer service executive
- Laundry operator
- Dry-cleaning operator
- Steam ironing staff
- Quality-control staff
- Packaging staff
- Pickup/delivery staff
When calculating working capital, consider not only salaries but also:
- Recruitment
- Training
- Uniforms
- Staff replacement
- Overtime where applicable
4. Include Rent & Security Deposit Separately
Rent is a monthly expense, but property-related costs can also include:
- Security deposit
- Advance rent
- Brokerage
- Registration-related expenses
- Initial renovation
These should generally be included in the initial setup budget, while monthly rent should be included in the ongoing operating budget.
This distinction helps prevent double-counting.
5. Plan for Utilities
Laundry operations can involve utilities such as:
- Electricity
- Water
- Internet
- Communication services
Actual utility requirements depend on:
- Equipment
- Processing volume
- Store format
- Location
- Operating hours
When creating your budget, use realistic local estimates rather than a generic industry figure.
6. Budget for Packaging & Consumables
Every order can involve operational materials.
Examples include:
- Garment covers
- Bags
- Tags
- Labels
- Hangers
- Packaging materials
- Cleaning-related consumables
At low order volumes, these expenses may be manageable.
As customer volume increases, however, the total requirement can grow significantly.
7. Include Pickup & Delivery Expenses
If your laundry business offers doorstep pickup and delivery, include:
- Delivery staff
- Fuel
- Vehicle costs
- Maintenance
- Route management
- Packaging
- Communication
A business that heavily depends on doorstep service may need a larger operating reserve than a store that primarily handles walk-in customers.
8. Don't Forget Marketing Expenses
A new laundry business needs customer acquisition.
Your working-capital planning should include an ongoing marketing budget for activities such as:
- Google Search
- Google Maps/local SEO
- Meta advertising
- Social media
- WhatsApp campaigns
- Residential society marketing
- Referral programs
- Local partnerships
Do not assume that a launch campaign alone will generate sufficient customers permanently.
9. Technology Costs
Modern laundry operations can use technology for:
- Order management
- Customer records
- Digital invoices
- Payments
- Pickup scheduling
- Delivery management
- Order tracking
- Reporting
If your technology system has recurring charges, include them in the monthly operating budget.
For franchise outlets, confirm which technology costs are included in the franchise arrangement and which are additional.
10. Maintenance Reserve
Equipment downtime can disrupt operations.
A working-capital plan should therefore account for potential:
- Machine servicing
- Repairs
- Replacement parts
- Electrical maintenance
- Plumbing
- Store repairs
The actual reserve depends on the equipment and operating model.
A separate maintenance reserve can help prevent unexpected repairs from immediately affecting day-to-day cash flow.
11. How Many Months of Working Capital Should You Keep?
There is no universal number that applies to every laundry business.
Instead, calculate your monthly cash requirement and then decide on a reserve based on:
- Expected customer ramp-up
- Monthly fixed expenses
- Variable costs
- Seasonality
- Local competition
- Owner's financial capacity
- Access to additional funding
A business with high fixed expenses may need a larger reserve than a lower-cost operation.
12. Simple Working Capital Calculation
A practical starting formula is:
Working Capital Reserve = Monthly Operating Cash Requirement × Reserve Period
For example, suppose your estimated monthly operating cash requirement is:
₹2,50,000
and you decide to maintain a hypothetical:
4-month operating reserve
Then:
₹2,50,000 × 4 = ₹10,00,000
So the illustrative reserve would be:
₹10 lakh
This is only an example. The appropriate reserve period should be determined from your own business plan.
13. Working Capital vs Initial Investment
These two concepts should not be confused.
Initial Investment
Money required to establish the business.
Examples:
- Store setup
- Equipment
- Interiors
- Branding
- Technology
- Property deposit
Working Capital
Money required to operate the business.
Examples:
- Rent
- Salaries
- Utilities
- Marketing
- Packaging
- Transportation
- Maintenance
A strong business plan should account for both.
14. Example Laundry Business Financial Plan
Suppose an entrepreneur has a hypothetical total project budget of:
₹25 lakh
They might divide their planning into:
| Category | Illustrative Allocation |
|---|---|
| Store setup & equipment | ₹15 lakh |
| Technology & branding | ₹2 lakh |
| Property-related costs | ₹3 lakh |
| Initial marketing | ₹1 lakh |
| Working capital reserve | ₹4 lakh |
| Total | ₹25 lakh |
This is an illustrative example only.
The actual allocation should be based on the business model and location.
15. Working Capital During the First 90 Days
The first three months can require careful cash-flow management.
Month 1
Focus on:
- Launch
- Customer acquisition
- Staff training
- Operational stabilization
Month 2
Focus on:
- Repeat customers
- Service quality
- Local marketing
- Cost control
Month 3
Focus on:
- Customer retention
- Revenue trends
- Service mix
- Operating efficiency
Instead of assuming immediate profitability, track actual numbers every month.
16. Create a Monthly Cash-Flow Sheet
A simple spreadsheet can contain:
| Metric | Month 1 | Month 2 | Month 3 |
|---|---|---|---|
| Revenue | ₹___ | ₹___ | ₹___ |
| Rent | ₹___ | ₹___ | ₹___ |
| Salaries | ₹___ | ₹___ | ₹___ |
| Utilities | ₹___ | ₹___ | ₹___ |
| Marketing | ₹___ | ₹___ | ₹___ |
| Transportation | ₹___ | ₹___ | ₹___ |
| Consumables | ₹___ | ₹___ | ₹___ |
| Maintenance | ₹___ | ₹___ | ₹___ |
| Other expenses | ₹___ | ₹___ | ₹___ |
| Net cash flow | ₹___ | ₹___ | ₹___ |
This gives you a clearer picture of how quickly your operating reserve is being used.
17. Watch Your Cash Conversion Cycle
Laundry businesses may receive customer payments relatively quickly, but some B2B customers may have different payment arrangements.
If you serve corporate customers, understand:
- Invoice cycle
- Credit period
- Payment terms
- Outstanding receivables
For example, if a corporate client pays after 30 days, you may have to fund operating expenses before receiving that revenue.
Therefore:
B2B revenue ≠ immediate cash
Cash-flow planning becomes particularly important as the business expands into corporate accounts.
18. Build an Emergency Reserve
Unexpected situations can affect operations.
Examples include:
- Equipment breakdown
- Staff replacement
- Temporary store disruption
- Unexpected repairs
- Higher-than-expected marketing costs
- Lower-than-expected customer demand
An emergency reserve can provide additional financial flexibility.
It should be separate from money required for normal monthly operations whenever possible.
19. Common Working Capital Mistakes
Mistake 1: Spending the entire budget on setup
A beautiful store cannot operate without sufficient working capital.
Mistake 2: Assuming immediate full capacity
Customer volume may take time to develop.
Mistake 3: Ignoring marketing costs
Customer acquisition requires ongoing effort.
Mistake 4: Underestimating salaries
Staff are a recurring expense.
Mistake 5: Forgetting maintenance
Equipment requires servicing and occasional repairs.
Mistake 6: Mixing personal and business funds
Maintain clear separation between personal and business finances.
Mistake 7: Ignoring B2B payment cycles
Corporate clients may have different payment terms.
20. How to Improve Working Capital Management
A laundry business can improve cash-flow management by:
Tracking daily revenue
Know how much money is being generated.
Monitoring expenses
Review actual expenses against the budget.
Managing inventory
Avoid unnecessary accumulation of consumables and packaging.
Controlling marketing spend
Measure customer acquisition rather than spending without tracking.
Improving repeat business
Repeat customers can reduce dependence on continuously acquiring new customers.
Monitoring receivables
Especially important for corporate/B2B customers.
Maintaining cash reserves
Avoid operating with zero financial buffer.
Working Capital Checklist for a Laundry Business
Before launching, calculate:
☐ Monthly rent
☐ Salaries
☐ Electricity
☐ Water
☐ Technology
☐ Marketing
☐ Packaging
☐ Consumables
☐ Pickup & delivery
☐ Maintenance
☐ Administrative expenses
☐ B2B payment cycle
☐ Emergency reserve
☐ Expected customer ramp-up
☐ Working-capital reserve period
Why Working Capital Matters for a Pick My Laundry Franchise
Pick My Laundry operates in the laundry and dry-cleaning industry with the following current brand proof points for this content strategy:
12+ Years of Industry Experience
500+ Stores
90+ Cities
Operations Across 4 Countries
For a prospective franchise owner, however, working-capital requirements should be calculated for the specific outlet, based on its location, format, rent, manpower, services, operating model and expected customer volume.
The broader brand network does not determine the financial requirements of an individual outlet.
Frequently Asked Questions
What is working capital in a laundry business?
Working capital is the financial resources available to manage ongoing business operations, including expenses such as rent, salaries, utilities, marketing, packaging and transportation.
Is working capital included in the franchise investment?
That depends on the specific franchise proposal. Always confirm whether the quoted investment includes working capital or whether it needs to be budgeted separately.
How much working capital does a laundry business need?
There is no universal amount. Calculate your monthly operating cash requirement and establish an appropriate reserve based on your expected customer ramp-up and business risks.
Why is working capital important for a new laundry business?
Because expenses continue even while a new store is building its customer base. Adequate working capital helps the business manage this initial operating period.
Should working capital be included in the business loan?
Depending on the financing structure, businesses may seek funding for both setup costs and working-capital requirements. The exact funding structure should be discussed with the relevant lender or financial advisor.
Can working capital requirements increase after opening?
Yes. Higher order volumes, expansion, additional staff, B2B contracts or new services can increase operating requirements.
Final Takeaway
Starting a laundry business requires more than paying for equipment and opening a store.
A sustainable financial plan should account for:
Setup Investment + Working Capital + Emergency Reserve
Before launching, calculate your expected monthly operating expenses, estimate the customer ramp-up period and maintain an appropriate cash reserve.
The objective is simple:
Don't just budget enough money to open the store. Budget enough to operate it responsibly.